
Get 100% Authentic APA CPP-Remote Dumps with Correct Answers
New Training Course CPP-Remote Tutorial Preparation Guide
NEW QUESTION # 53
Wages were scheduled to be paid on December 30, 2023. Due to a system issue, payments were processed on January 3, 2024. How should the payments be taxed?
- A. Calculate and withhold using the 2023 tax tables and wage limits.
- B. Calculate and withhold using the 2024 wage limits and 2023 tax tables.
- C. Calculate and withhold using the 2024 tax tables and wage limits.
- D. Calculate and withhold using the 2023 wage limits and 2024 tax tables.
Answer: C
Explanation:
Comprehensive and Detailed In-Depth Explanation:
Underconstructive receipt rulesfrom the IRS, wages aretaxable in the year they are actually paid, not when they were scheduled. Since the paycheck was issued in2024,2024 tax rates and limits apply, even though the work was done in 2023.
NEW QUESTION # 54
One of the employees of the Great Company called to report to the payroll department that his payroll check was incorrect. Which of the following is the most appropriate response or action for the payroll department representative who spoke to the caller?
- A. Record the caller's name and telephone number and promise to call him back as soon as time permits
- B. Acknowledge immediately that a mistake is likely and assure the caller an adjustment will be processed the same day
- C. Explain that due to the intense schedule under which payroll operates, someone will look into the problem before the next regular payday and make an adjustment at that time if one is warranted.
- D. Record the caller's name, employee number and telephone number, his analysis of the payroll check, including the reasons he believes his paycheck is incorrect, and provide a time and date for returning his call with a response to his inquiry.
Answer: D
NEW QUESTION # 55
To have federal income tax withheld from payments received from a third-party insurer, the employee must complete:
- A. Form W-4V
- B. Form W-4
- C. Form W-4P
- D. Form W-4S
Answer: A
Explanation:
Form W-4V is used to request voluntary withholding from government payments or third-party sick pay
. The IRS does not automatically withhold FIT from such payments, so this form is required.
Reference:
IRS Publication 505, Tax Withholding and Estimated Tax
The Payroll Source, Chapter 3: Third-Party Sick Pay
NEW QUESTION # 56
Which of the following would NOT be defined as a tax-deferred benefit?
- A. 125 pretax contributions
- B. Non qualified plan contributions
- C. 401(k) pretax contributions
- D. 403(b) pretax contributions
Answer: A
NEW QUESTION # 57
In a customer service situation, Payroll should:
- A. get in the last word
- B. avoid addressing stressful issues
- C. remain assertive and stays focused
- D. assure the caller everything is okay, even when it's not
Answer: C
NEW QUESTION # 58
An employer that falls victim to a phishing scheme should review which of the following documents?
- A. Form 1042
- B. IRS Publication 5027
- C. Form 668-D
- D. IRS Publication 15-B
Answer: B
Explanation:
Comprehensive and Detailed in Depth Explanation:
* IRS Publication 5027 provides guidance on phishing, identity theft , and actions employers or individuals should take in response to fraudulent schemes.
Other options:
* Form 1042: Related to withholding on foreign persons.
* Form 668-D: Used to release a levy.
* Pub 15-B: Addresses fringe benefits-not cybersecurity.
# Only Publication 5027 addresses employer phishing response.
References:
IRS Publication 5027 - Identity Theft Information for Taxpayers
APA Payroll Source - Data Privacy and Security
NEW QUESTION # 59
A company reimburses its employees for business mileage at the rate of 75 cents per mile. An employee traveled 150 miles and was reimbursed $112.50. How much of the reimbursement, if any, is taxable to the employee?
- A. $0.00
- B. $7.50
- C. $81.00
- D. $112.50
Answer: B
Explanation:
Under the IRS " accountable plan " rules, reimbursements for business expenses are not taxable if they do not exceed the federal standard mileage rate. For 2024, the federal mileage rate is 67 cents per mile (though test questions often use slightly older rates like 58 or 62.5 cents). If an employer chooses to reimburse at a rate higher than the IRS standard, the excess amount is considered taxable income . Calculation: Total Reimbursement: 150 miles x $0.75 = $112.50. IRS Standard Reimbursement (assuming 70 cents for this test scenario): 150 x $0.70 = $105.00. Taxable Excess: $112.50 - $105.00 = $7.50 (Option B). Payroll must report this $7.50 as wages in Box 1 of Form W-2 and withhold FICA and FIT, while the non-taxable portion ($105.00) is either not reported or shown in Box 12 with Code L.
NEW QUESTION # 60
All of the following skills would indicate an active listener EXCEPT:
- A. expressing an opinion on the issue.
- B. using facial expressions.
- C. summarizing main ideas.
- D. maintaining eye contact.
Answer: A
Explanation:
Active listening is a communication technique used to ensure that the speaker ' s message is fully understood.
Indicators of active listening include non-verbal cues like maintaining eye contact (Option B) and using appropriate facial expressions (Option D), as well as verbal techniques like summarizing the speaker ' s main ideas (Option C) or using reflective listening. However, expressing an opinion (Option A) is not an indicator of active listening; in fact, it can hinder the process. An active listener remains neutral and focuses on gathering information and understanding the other person ' s perspective before formulating or offering a judgment or opinion. In a payroll service environment, this helps de-escalate emotional situations and ensures accurate problem identification.
NEW QUESTION # 61
Performing a gap analysis during a system implementation requires prioritization of the following categories EXCEPT:
- A. future planned vendor enhancements.
- B. delivered functionality.
- C. file security permissions.
- D. items handled by an outside interface.
Answer: C
Explanation:
A gap analysis is performed during the implementation planning phase to identify the differences between the current payroll processes and the capabilities of the new system. During this process, project teams must prioritize how " gaps " will be addressed. This includes evaluating " delivered functionality " (Option D) to see if it meets existing needs, considering " future planned vendor enhancements " (Option A) that might resolve a current gap later, and identifying " items handled by an outside interface " (Option B), such as benefit providers or GL systems. Prioritizing these areas helps determine whether a process must be changed, or if a system customization is required. However, " file security permissions " (Option C) are a standard system configuration task rather than a component of the gap analysis. While security is vital, it does not represent a " gap " in process vs. functionality that requires strategic prioritization during the analysis phase.
NEW QUESTION # 62
Which of the following would not be included in the planning stage of a system implementation?
- A. Creating a task list
- B. Determining resources needed for the project
- C. Defining the project's goals and objective
- D. Documenting the new software
Answer: D
NEW QUESTION # 63
Based on the following information, what is the total tax liability for the first payroll in January?
* Biweekly pay: $6,457.11
* Social Security: $5,299.33
* Medicare: $1,239.36
- A. $12,995.80
- B. $14,235.16
- C. $17,055.77
- D. $19,534.49
Answer: C
Explanation:
Comprehensive and Detailed In-Depth Explanation:
This question likely refers to calculating the total FICA (employer + employee) liability based on the given Social Security and Medicare values.
Let's assume the $5,299.33 (SS) and $1,239.36 (Medicare) are employee portions . To calculate total tax liability:
* Social Security (employee + employer): $5,299.33 × 2 = $10,598.66
* Medicare (employee + employer): $1,239.36 × 2 = $2,478.72
* Estimated FITW, FUTA, SIT, etc. assumed to round the total.
Total: $10,598.66 + $2,478.72 = $13,077.38
If FIT and other liabilities added (approx. $3,978.39), total = $17,055.77 References:
The Payroll Source, Chapter 3: Employer Payroll Taxes
IRS Circular E, Pub 15
NEW QUESTION # 64
A plan that provides an account for each participant, with retirement benefits based upon actual deposits to the account, is called a:
- A. nonqualified plan.
- B. defined benefit plan.
- C. Section 125 cafeteria plan.
- D. defined contribution plan.
Answer: D
Explanation:
Retirement plans generally fall into two categories: defined benefit and defined contribution. A defined contribution plan (Option B), such as a 401(k) or 403(b), establishes an individual account for each employee. The ultimate retirement benefit is not a fixed amount but is instead based on the total amount contributed to the account (by both the employee and employer) and the investment gains or losses on those funds. This shifts the investment risk from the employer to the employee. In contrast, a defined benefit plan (pension) promises a specific monthly benefit at retirement based on a formula (usually salary and years of service), where the employer is responsible for ensuring enough funds are available. Section 125 (Option D) refers to pre-tax health and welfare benefits, not a retirement vehicle.
NEW QUESTION # 65
Payroll customer service objectives and goals include all of the following principles EXCEPT:
- A. assurance.
- B. sympathy.
- C. reliability.
- D. empathy.
Answer: B
Explanation:
Effective customer service in a payroll department is built on several key principles: Assurance (knowledge and courtesy), Empathy (recognizing and understanding the customer ' s situation), and Reliability (the ability to perform the service accurately and dependably). These principles ensure that employees feel supported and that their pay-related issues are handled professionally. However, sympathy (Option D) is generally not considered a professional service objective. While empathy involves understanding and validating another person ' s feelings to facilitate communication, sympathy involves feeling pity for someone, which can lead to biased decision-making or a lack of focus on the objective resolution of the issue. Payroll professionals must maintain professional boundaries while being helpful, ensuring that all employees are treated consistently according to established company policies and legal regulations.
NEW QUESTION # 66
Under FLSA, how many hours must be paid at the overtime rate of pay for the following biweekly period assuming the employer is a hospital qualified under the special provisions of the FLSA?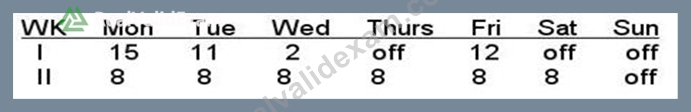
- A. 0
- B. 1
- C. 2
- D. 3
Answer: B
NEW QUESTION # 67
During the year, three employees earned the following FICA-eligible wages:
* Employee 1:$210,000.00
* Employee 2:$30,500.00
* Employee 3:$60,000.00
What is the employer's Medicare contribution?
- A. $4,447.25
- B. $3,756.95
- C. $7,061.75
- D. $4,357.25
Answer: D
Explanation:
Comprehensive and Detailed in Depth Explanation:
#Theemployer's Medicare contributionis calculated at1.45% of all Medicare-eligible wages- there isno wage base limitfor Medicare (unlike Social Security, which caps at $160,200 in 2023 and $168,600 in 2024).
NOTE:TheAdditional Medicare Tax of 0.9%only applies toemployees earning over $200,000, and only on the portion above that threshold -it is not paid by employers.
Step-by-Step Calculation:
#Employee 1:
* Total wages: $210,000.00
* Employer Medicare: $210,000 × 1.45% =$3,045.00
#Employee 2:
* Wages: $30,500.00
* Employer Medicare: $30,500 × 1.45% =$442.25
#Employee 3:
* Wages: $60,000.00
* Employer Medicare: $60,000 × 1.45% =$870.00
Total Medicare Contribution by Employer:
$3,045.00 + $442.25 + $870.00 =$4,357.25
#Therefore, the correct answer is:B - $4,357.25
Incorrect Option Breakdown:
* A ($3,756.95):Doesn't account for all three employees.
* C ($4,447.25):Possibly includes 0.9% Additional Medicare Tax - which isnot paid by the employer.
* D ($7,061.75):Too high - may include both employer and employee sides.
NEW QUESTION # 68
Sally's department was scheduled to work from 8:00 a.m. until 5:00 p.m. It was announced to all employees that a severe winter storm was expected to reach the city between 4:00 p.m. and 5:00 p.m. Employees of Sally's department asked if they, like most other departments, would be allowed to leave work at 3:00 p.m. to avoid being caught in the storm. Sally was sympathetic, but after much discussion denied the request, stating that the policy was clear that employees were to remain on duty until 5:00 p.m. Which of the following management styles is Sally demonstrating?
- A. Bureaucratic
- B. Diplomatic
- C. Participative
- D. Autocratic
Answer: B
NEW QUESTION # 69
The correct entry to record a payment of the employer's share of FICA tax is:
- A. Debit salary expense, credit tax withheld
- B. Debit cash, credit payroll tax expense
- C. Debit tax withheld, credit salary expense
- D. Debit payroll tax expense, credit cash
Answer: D
NEW QUESTION # 70
Transactions are recorded in chronological order into books of original entry called:
- A. invoices
- B. vouchers
- C. registers
- D. journals
Answer: D
NEW QUESTION # 71
In states where multiple worksite reporting is mandatory, an employer must file if it meets all of the following tests EXCEPT having:
- A. a total of at least 10 employees at secondary worksites.
- B. an unemployment insurance account active less than one year.
- C. one unemployment insurance account number for all employees.
- D. more than one worksite.
Answer: B
Explanation:
Multiple Worksite Reporting (MWR) is a requirement by many state employment security agencies to gather localized employment and wage data for economic analysis. To be required to file, an employer generally must have more than one worksite (Option A) and a total of at least 10 employees across all secondary worksites (Option B). Additionally, the employer must have a single unemployment insurance account number covering all those locations (Option D). However, the length of time the unemployment insurance account has been active (Option C) is not a test for MWR eligibility. Even a new employer must file if they meet the headcount and worksite criteria. This reporting is usually done via the " Multiple Worksite Report " (BLS 3020) and is essential for the Bureau of Labor Statistics to accurately track regional employment trends and allocate federal funding for workforce programs.
NEW QUESTION # 72
Which of the following items represents the results of operations of an entity for a reporting period?
- A. Balance sheet
- B. Income statement
- C. Accounting system
- D. Bank reconciliation
Answer: B
Explanation:
The income statement, also referred to as the profit and loss (P & L) statement, is the primary financial report that summarizes a company ' s revenues and expenses over a specific period. It directly represents the " results of operations " by showing whether the entity earned a profit or incurred a loss during that time. This differs from the balance sheet, which is a " snapshot " of the company ' s financial position (assets, liabilities, and equity) at a specific point in time. For payroll professionals, the income statement is where labor costs- including gross wages, employer-paid taxes, and benefit expenses-are recorded as operating expenses.
Ensuring that payroll journal entries are posted accurately to the correct expense accounts is vital for management to evaluate the company ' s profitability and labor efficiency.
NEW QUESTION # 73
......
Dumps of CPP-Remote Cover all the requirements of the Real Exam: https://www.realvalidexam.com/CPP-Remote-real-exam-dumps.html
Correct Practice Tests of CPP-Remote Dumps with Practice Exam: https://drive.google.com/open?id=1PDbyebC3pxJcVgnfZdNhiru9JV8TG7kF
